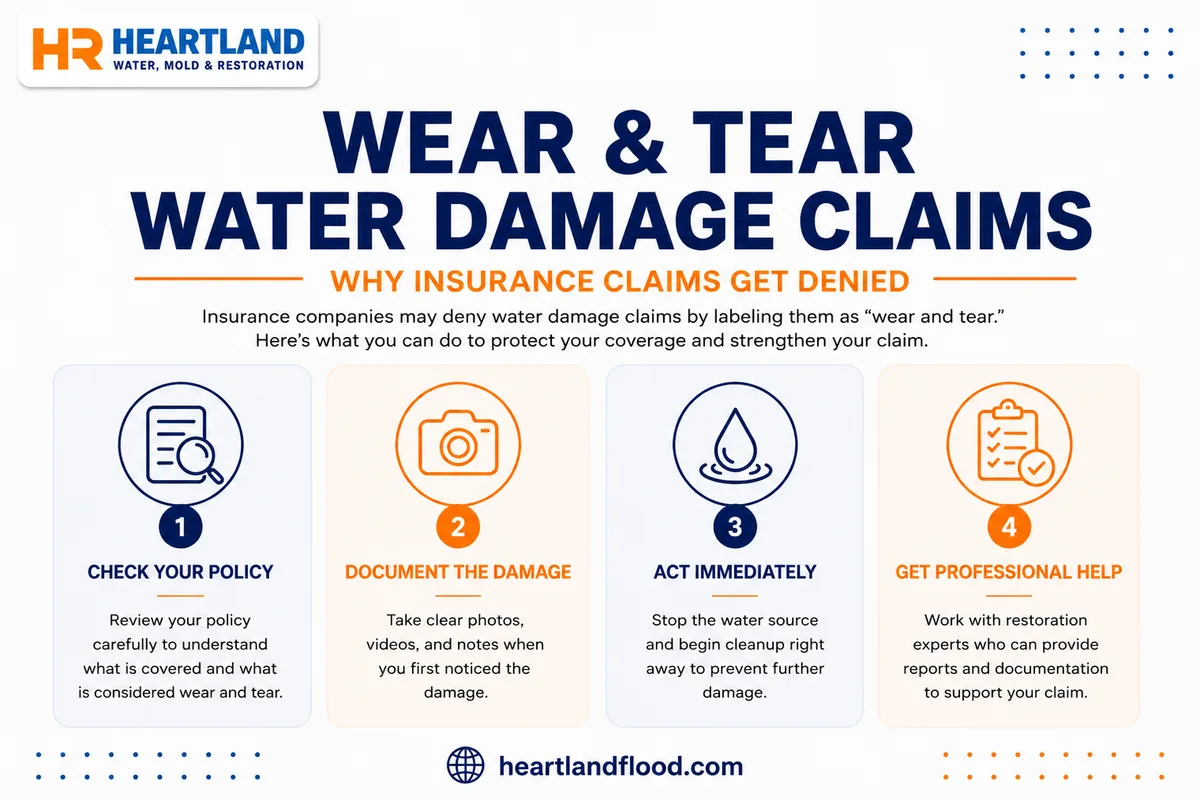
Quick answer: Insurers classify water damage as wear and tear when they believe it developed gradually rather than from a sudden, accidental event, and policies exclude gradual deterioration. To protect a claim, report the loss within a day or two, have a professional take moisture readings before cleanup, keep a drying log with photos, and gather maintenance records. The first 48 hours of documentation often decide how the claim is classified.
A homeowner calls a restoration crew after finding a soft spot in the hallway floor. The water gets extracted, the drywall comes down, and everyone assumes the insurance company will cover it. Three weeks later, a letter arrives citing wear and tear water damage as the reason for denial. No storm on record, no burst pipe listed as the cause, just a line item that shifts a five-figure repair back onto the family that filed the claim.
This happens constantly, and it's rarely because the homeowner did anything wrong. A water damage insurance claim gets denied under this label whenever the cause isn't airtight, because the term itself is one of the vaguest phrases written into a homeowners policy. Understanding how adjusters build that case, and how restoration professionals document a loss to counter it, is the difference between a fully funded repair and a fight that drags on for months.
What Is Wear and Tear Water Damage, and Why Do Insurers Use the Term?
Every standard homeowners policy separates sudden, accidental losses from the slow breakdown of a home's materials over time. Insurers write policies to cover the first category and exclude the second. That distinction sounds clean on paper. It gets complicated fast once you're the one trying to prove which side your leak falls on.
How Policy Language Creates Room for an Insurance Claim Denial
Policy exclusions typically reference "deterioration," an "inherent defect," or damage that developed "over a period of weeks, months, or years." That phrasing is deliberately elastic. A pipe that failed in an instant can still be described as having "likely been weakening for some time," and once that sentence lands in a claims file, the burden shifts to the homeowner to prove otherwise.
The Financial Incentive Behind a Wear and Tear Denial
There's a financial reality worth naming here. A wear and tear classification is the cheapest possible outcome for an insurer. If a corroded fitting can be framed as slow degradation instead of a sudden rupture, the loss moves off the insurer's books entirely. That doesn't make every insurance claim denial bad faith. It means the classification gets applied liberally, and homeowners who understand the reasoning behind it are far better positioned to challenge it.
Sudden and Accidental Water Damage vs Gradual Deterioration
Coverage almost always comes down to one distinction: was the failure sudden and accidental water damage, or did it develop over time from neglect?
Burst Pipes and Frozen Pipe Failures
Burst pipe damage is the clearest example of a sudden loss. A pipe doesn't slowly become "more burst" over a month, it's intact, then it isn't. This matters a great deal in a region where a hard freeze can hit in January after a mild stretch of weather, catching homeowners who haven't insulated exposed plumbing in a crawlspace or garage. A frozen pipe that splits during that freeze often goes unnoticed until it thaws days later, which is exactly the kind of delay an adjuster will point to as evidence of a long-standing issue rather than a single, sudden event.
Appliance Leaks That Get Mistaken for Long-Term Wear
A refrigerator water line leak can soak a subfloor for months behind an appliance nobody moves, and by the time it's discovered, the damage looks like it's been building for a long time, even if the line itself failed abruptly. The same pattern shows up with an overflowing dishwasher, where a failed door seal lets small amounts of water escape for weeks before a full backup finally floods the kitchen. A washing machine hose that ruptures follows the opposite pattern; it's usually sudden and obvious, which is why those claims tend to get approved far more easily.
Roof Leaks After Storm Damage
A roof leak water damage claim carries its own complications, especially after hail storms move through the Midwest each spring. If a roof already had some granule loss or a few lifted shingles before the storm, an adjuster may argue the water intrusion traces back to pre-existing wear rather than storm damage, even when the hail impact is what actually opened the path for water. This shows up constantly in Kansas and Missouri homes after spring storm season, when a roof that looked fine in March starts leaking by June.
How Insurance Adjusters Investigate a Water Damage Claim
An insurance adjuster isn't just deciding whether damage exists. They're reconstructing a timeline to determine whether the cause fits inside the policy's definition of a covered loss.
What Adjusters Look For During a Property Damage Inspection
A property damage inspection typically includes moisture readings at the point of loss, a visual assessment of the surrounding materials, and a comparison against any maintenance or repair history on file. Adjusters are trained to look for staining patterns, mineral deposits around fittings, and the condition of insulation and framing near the source. Fresh water intrusion behaves differently than water that's been sitting for weeks, and an experienced adjuster can often tell the difference just from how far moisture has traveled through drywall and subfloor.
How Claim Timelines Affect the Outcome
The gap between when damage likely began and when it was reported carries more weight than most homeowners expect. Report a leak within a day or two of noticing it, and the sudden-event argument holds up well. Let three months pass because a sound coming from the wall didn't seem urgent, and the insurer has a much easier case for gradual deterioration, even if the failure itself happened in a single moment.
Hidden Water Leaks and the Role of Moisture Inspection
Hidden water leaks are where most wear and tear disputes originate, because the damage is discovered long after the failure occurred.
A pinhole leak inside a wall cavity can run for two or three weeks before staining shows up on the surface. By the time anyone notices, the adjuster sees weeks of water exposure and assumes weeks of slow deterioration, when what actually happened is a fitting failed on day one and nobody knew it yet.
Why Hidden Moisture Leads to Secondary Damage and Mold Risk
A proper moisture inspection doesn't stop at the visible stain. Trained technicians check adjacent wall cavities, subfloor, and insulation for hidden moisture that hasn't surfaced yet, because untreated dampness behind a wall is exactly how secondary damage develops: warped framing, delaminated subfloor, and the conditions that support mold prevention failures within 24 to 48 hours of sustained moisture. This is one of the biggest reasons a fast, thorough inspection matters. Mold growth that develops after a slow, undocumented leak is far more likely to trigger a separate coverage dispute, since mold exclusions are often even stricter than water damage exclusions.
How Restoration Companies Document a Water Damage Loss
The documentation a water restoration company produces in the first 24 to 48 hours often decides how a claim gets classified, sometimes more than anything that happens in the weeks that follow.
Drying Documentation and Why It Matters for Your Claim
Water mitigation work involves more than pulling out wet materials and running fans. Technicians log moisture readings at regular intervals throughout the drying process, creating a data trail that shows exactly how saturated the structure was on day one and how it progressed toward dry standard. That drying log is often the single strongest piece of evidence against a wear and tear denial, because it can show water was confined to a pattern consistent with a specific point of failure rather than long-term seepage.
Moisture Mapping and Structural Drying in Practice
Moisture mapping uses meters to chart exactly how far water traveled through walls, flooring, and framing. Combined with photos, thermal imaging where needed, and a written scope of loss, it gives an adjuster a far more precise picture than a homeowner's visual description. Structural drying logs, moisture maps, and photo documentation together form the backbone of a defensible claims file.
Crews at Heartland Restoration build this kind of documentation into every job from the first site visit, not as an afterthought once a denial letter shows up. That habit is what separates a claim that gets fully funded from one that turns into a months-long appeal.
What to Do When a Wear and Tear Claim Is Denied
A denial letter isn't the end of the process, even though it's written to sound final.
Building an Appeal With Maintenance Records
Insurers are required to cite the specific policy language behind a denial, and that citation is the starting point for an appeal. Maintenance records carry real weight here. A homeowner who can produce a receipt for a water heater flush eighteen months ago, or a plumber's inspection report from the previous year, has direct evidence that undercuts a wear and tear argument. Insurers can't easily claim neglect against a maintenance record that says otherwise.
When to Bring in a Public Adjuster or Attorney
For larger losses, involving a public adjuster or an attorney who handles property insurance disputes regularly can uncover coverage the original denial missed, since these professionals know which policy provisions insurers tend to misapply. A Kansas City water damage restoration crew that works these disputes regularly can also speak directly to the local carriers, which matters more than people expect. The same insurers show up on repeat claims across the metro, and crews who've been through the appeal process with them know exactly which documentation moves a file forward.
Preventing Wear and Tear Disputes Before They Start
Most of what protects a homeowner in a dispute gets built long before any water touches the floor, and this matters even more in older homes across Kansas and Missouri, where original plumbing and aging roofing are common.
- Keep receipts and service records for plumbing inspections, water heater maintenance, and roof repairs
- Schedule a seasonal check of supply lines, appliance hoses, and roof flashing, especially before winter freezes and after spring storms
- Insulate exposed pipes in crawlspaces, garages, and unheated additions before the first hard freeze
- Call for professional help immediately at the first sign of moisture rather than waiting to see if it dries out on its own
An emergency water damage restoration call within hours of discovering a leak, rather than days, is often what keeps a claim in the sudden-and-accidental category in the first place. Heartland Restoration responds quickly and documents thoroughly from the start give homeowners a real advantage before an adjuster ever walks through the door.
The Real Lesson in Every Wear and Tear Dispute
The claims that survive a wear and tear challenge almost always share the same pattern: fast reporting, early documentation, and a professional moisture inspection completed before cleanup started. The ones that don't survive usually lose the argument in the first 48 hours, not in the appeal process.
If there's one thing worth remembering the next time a pipe fails at 11 p.m. or a storm leaves a stain spreading across the ceiling, it's this: the strength of your claim is decided by what gets documented before the insurance company ever sees the damage, not by how convincingly you explain it afterward.
Related Reading
- Water Damage Comparison Guide: Mitigation vs Restoration, DIY vs Professional, and Flood Damage Explained
- 24/7 Emergency Water Damage Response: What Happens in the First Hour and What It Costs
- Does homeowners insurance cover water damage?
- How to Choose a Water Damage Restoration Company: A Complete Checklist
Last updated October 3, 2026
Frequently Asked Questions About Wear and Tear Water Damage Claims
Does homeowners insurance cover a slow leak that was never noticed?
Coverage depends on whether the underlying failure was sudden, even if it went undetected for a time. A slow leak with no identifiable sudden cause is much harder to get covered, because policies exclude gradual deterioration. Prompt reporting and a professional moisture inspection help show when and how the loss began.
Can a restoration company report override an adjuster denial?
It cannot override a denial outright, but a documented moisture inspection, moisture map, and drying log can give the insurer new evidence about the cause and timeline, and often supports a reversal on appeal. It works best alongside the policy language the insurer cites and your maintenance records.
How quickly does mold start growing after a water leak?
Under the right conditions mold can begin forming within 24 to 48 hours of sustained moisture. That is why fast mitigation matters for health and for coverage, since mold that develops after a slow, undocumented leak can trigger a separate dispute, and mold exclusions are often stricter than water damage exclusions.
Is water damage from an old roof automatically excluded?
Not automatically. If a specific storm event such as hail created the opening for water, that event can still be the covered cause even if the roof had some existing wear. Adjusters may argue pre-existing wear, so photos and a documented inspection after the storm matter.
What is the difference between water mitigation and water restoration?
Mitigation is the emergency work that stops further damage, such as extraction, drying, and removal of unsalvageable materials. Restoration is the rebuild that follows, such as drywall, flooring, and paint. Documentation from the mitigation phase often decides how a claim is classified.
Do insurance companies require a set number of moisture readings?
There is no universal standard, but most carriers expect readings logged at intervals through the drying process to show the structure reached an acceptable dry standard. Professional crews record readings at documented test points on each monitoring visit, which creates a data trail from day one to dry.
Can I dispute a denial without a public adjuster?
Yes. A written appeal that cites the policy language, with an independent inspection and maintenance records, is often enough. For larger or contested losses, a public adjuster or an attorney who handles property insurance disputes can help. Read your policy and state rules, and treat this as general information, not legal advice.
Does filing a water damage claim raise my rates?
It can, especially for a second water-related claim within a few years, and the effect depends on the insurer and your history. That is one more reason preventive maintenance and fast leak detection matter beyond the immediate repair cost. Ask your agent how a claim could affect your premium.
Sources & References
- ANSI/IICRC S500 Standard for Professional Water Damage Restoration - IICRC (Institute of Inspection, Cleaning and Restoration Certification)
- National Flood Insurance Program - Flood Insurance & Recovery Guidance - FEMA (Federal Emergency Management Agency)
- National Weather Service Flood Safety - NOAA National Weather Service
Comments
No comments yet.